Is AI actually allowed in insurance?
Do you need to wait for a dedicated law, or a green light from the ACPR (the French insurance supervisor), before launching AI-powered products and modules? It’s a question many insurers, brokers and MGAs are asking right now.
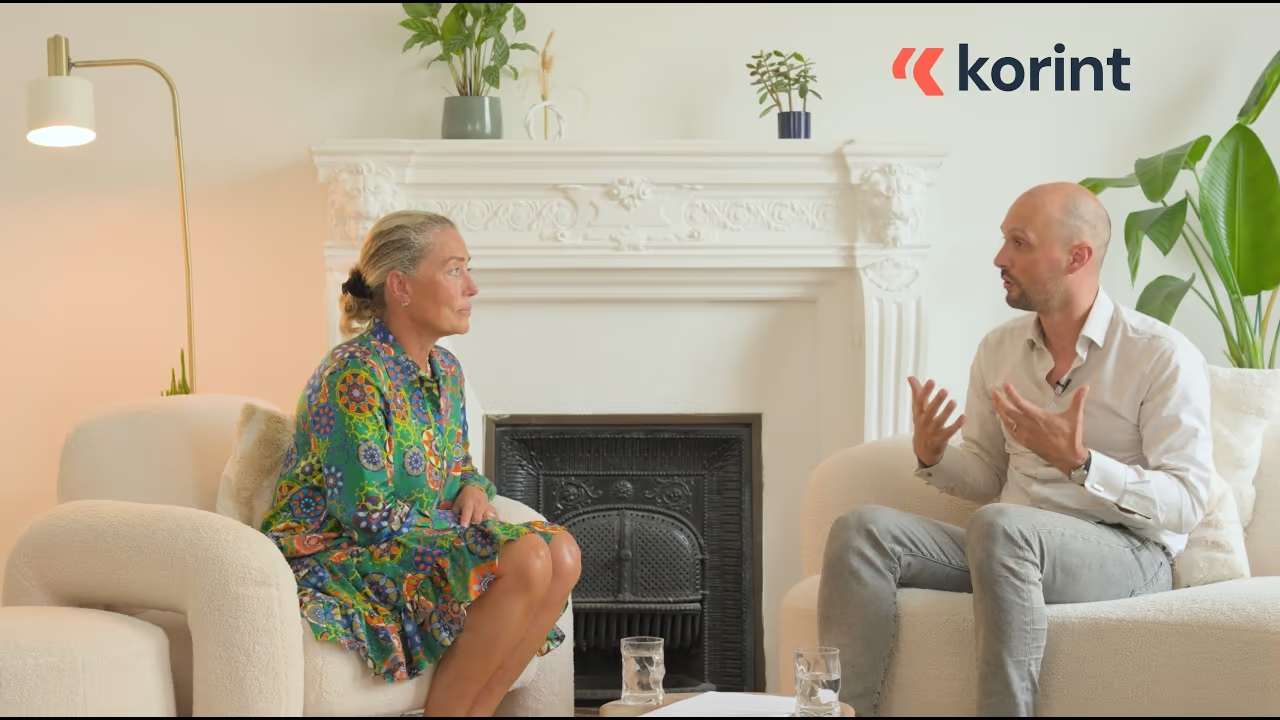
To answer it, Jean-Baptiste Limare, CEO and co-founder of Korint, is joined by Isabelle Monin-Lafin, founding lawyer at Astrée Avocats and a specialist in financial-sector distribution. Together, they unpack what AI means for insurance, with the texts and the examples to back it up. The conversation is in French.
The framework: the AI Act and distributor liability
The first part of the discussion covers the framework set by the European AI Act, and what it does (and doesn’t) change for insurance players. Isabelle Monin-Lafin also looks at distributor liability: who is answerable for what when an AI tool steps into the sales or servicing journey.
Five use cases under the microscope
The second part works through very concrete use cases, already found in the field.
- Automated quotes
- Spotting coverage gaps
- Policy amendments
- Talking with non-French-speaking customers
- Fraud detection
For each one, they assess the level of risk and the place the human keeps in the decision.
Going further
Want to see how Korint brings AI into your policy administration, within a controlled framework? Discover Korint Companion, or talk to our team.